

When a new general purpose technology arrives (think railroads, electricity, the internet, etc), this is typically accompanied by a huge boom in infrastructure investment, as private investors start building the infrastructure that is needed to deploy this new technology. We are currently experiencing on of these GPT-fueled investment boom in the U.S.
Total US AI-infrastructure investment was $1.15 trillion in 2025 and is projected to reach $1.43 trillion in 2026. According to my long-time co-author Stijn Van Nieuwerburgh’s fascinating BPEA paper, “Financing the AI buildout”, the U.S. is projected to invest roughly 3.6% of GDP in AI infrastructure (think data centers etc) between 2025 and 2032. That is about three times the size of the US telecom and fiber investment boom in the late 90s. And it’s roughly 50% larger than the railroad investments of the late 19th century. This is shaping up to be one of the largest infrastructure investment booms in U.S. history.
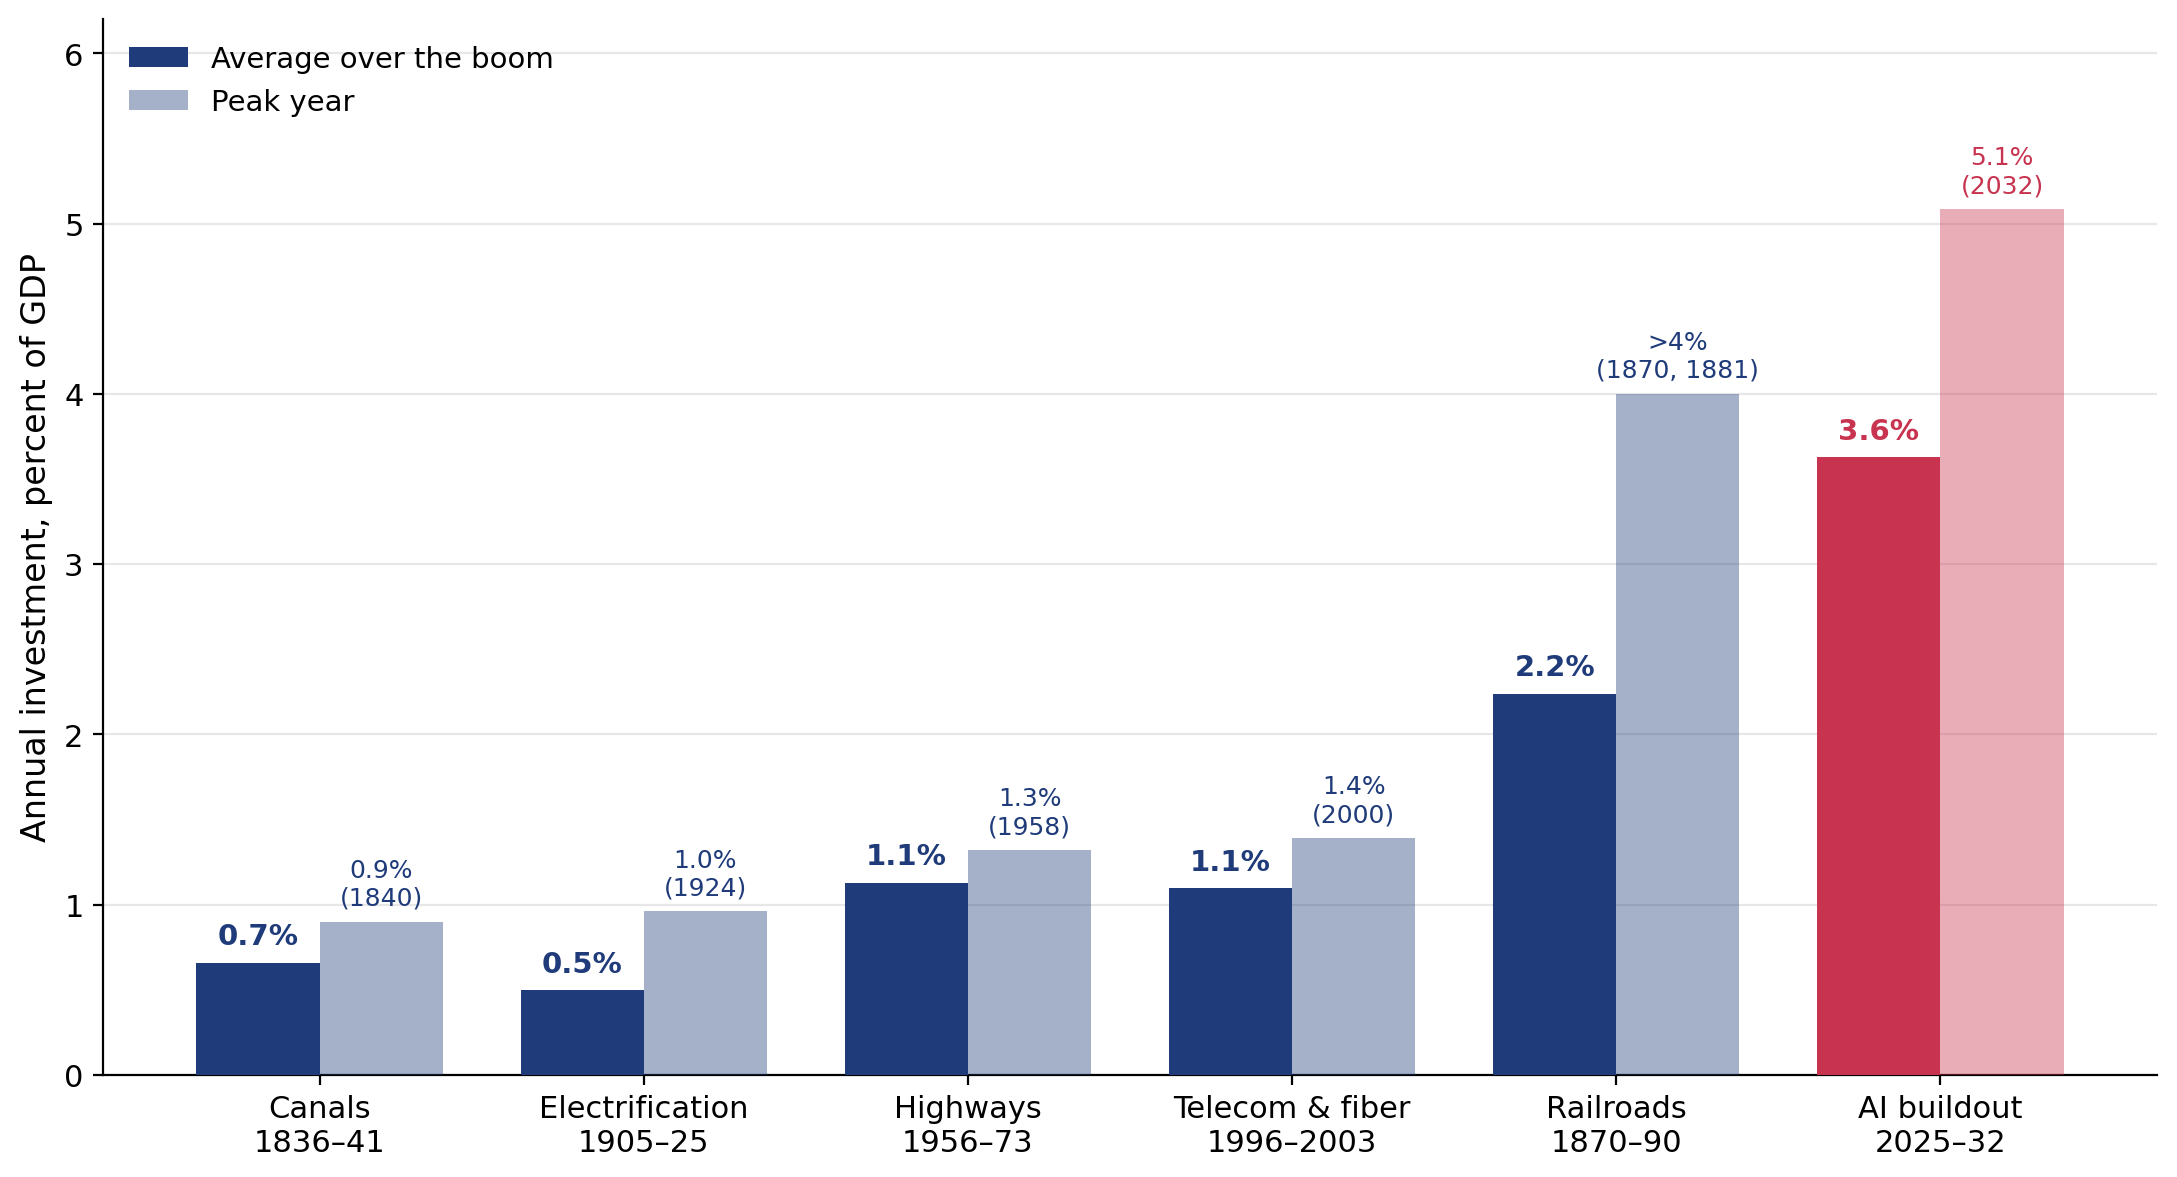
In truth, these numbers are hard to compare. The railroad boom lasted 20 years. Railroads also depreciate much slower than data centers. Rails last a lot longer than GPUs.
What do you have to believe about future revenue in order for all data center owners to to break even on their AI investment? Using a 10% discount rate, Stijn’s baseline number is 3.725 trillion of annual revenue by 2032, which would amount to roughly 9.2% of projected 2032 GDP.1 This number is the top line earned from selling compute in aggregate by whoever operates the 182.7 GW of US capacity completed by 2032.2 Today’s U.S. compute revenue base is on the order of $0.3 trillion. To reach $4 trillion by 2032, total data-center revenue needs to grow at roughly 45% per year for seven years.
The assumptions behind that number:
183 GW of U.S. data-center capacity completed between 2025 and 2032
$8.54 trillion of construction cost, grossed up to a $9.61 trillion capital base to account for the return on capital tied up during construction
A 10% discount rate
A 6-year life for IT equipment (68% of cost) and a 20-year life for everything else (32%)
A 50% operating cash flow margin
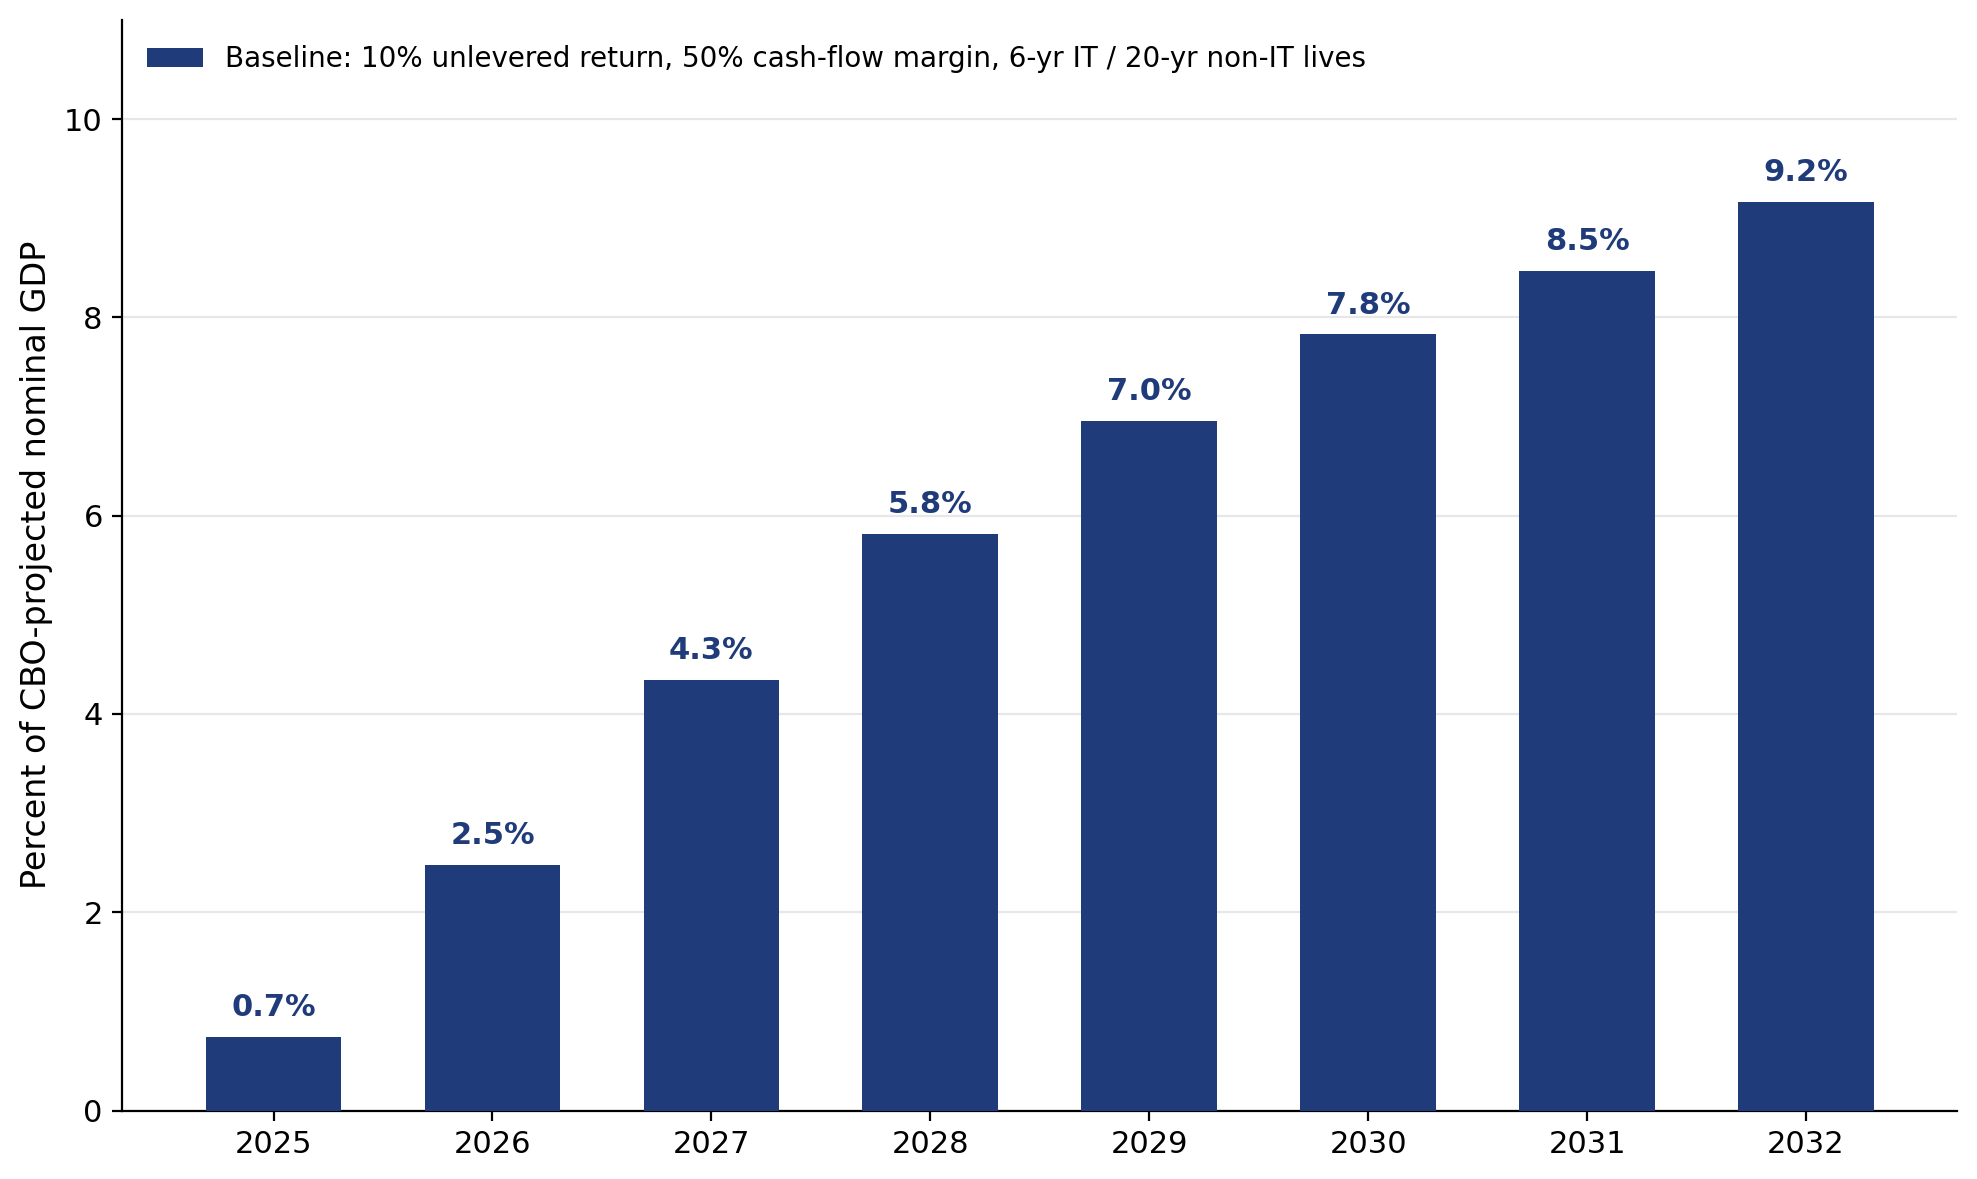
In a recent, excellent blog post on the same topic, Jared Bernstein and Ryan Cummings come up with similar numbers for the hyperscalers, using a slightly different approach and a perspective.
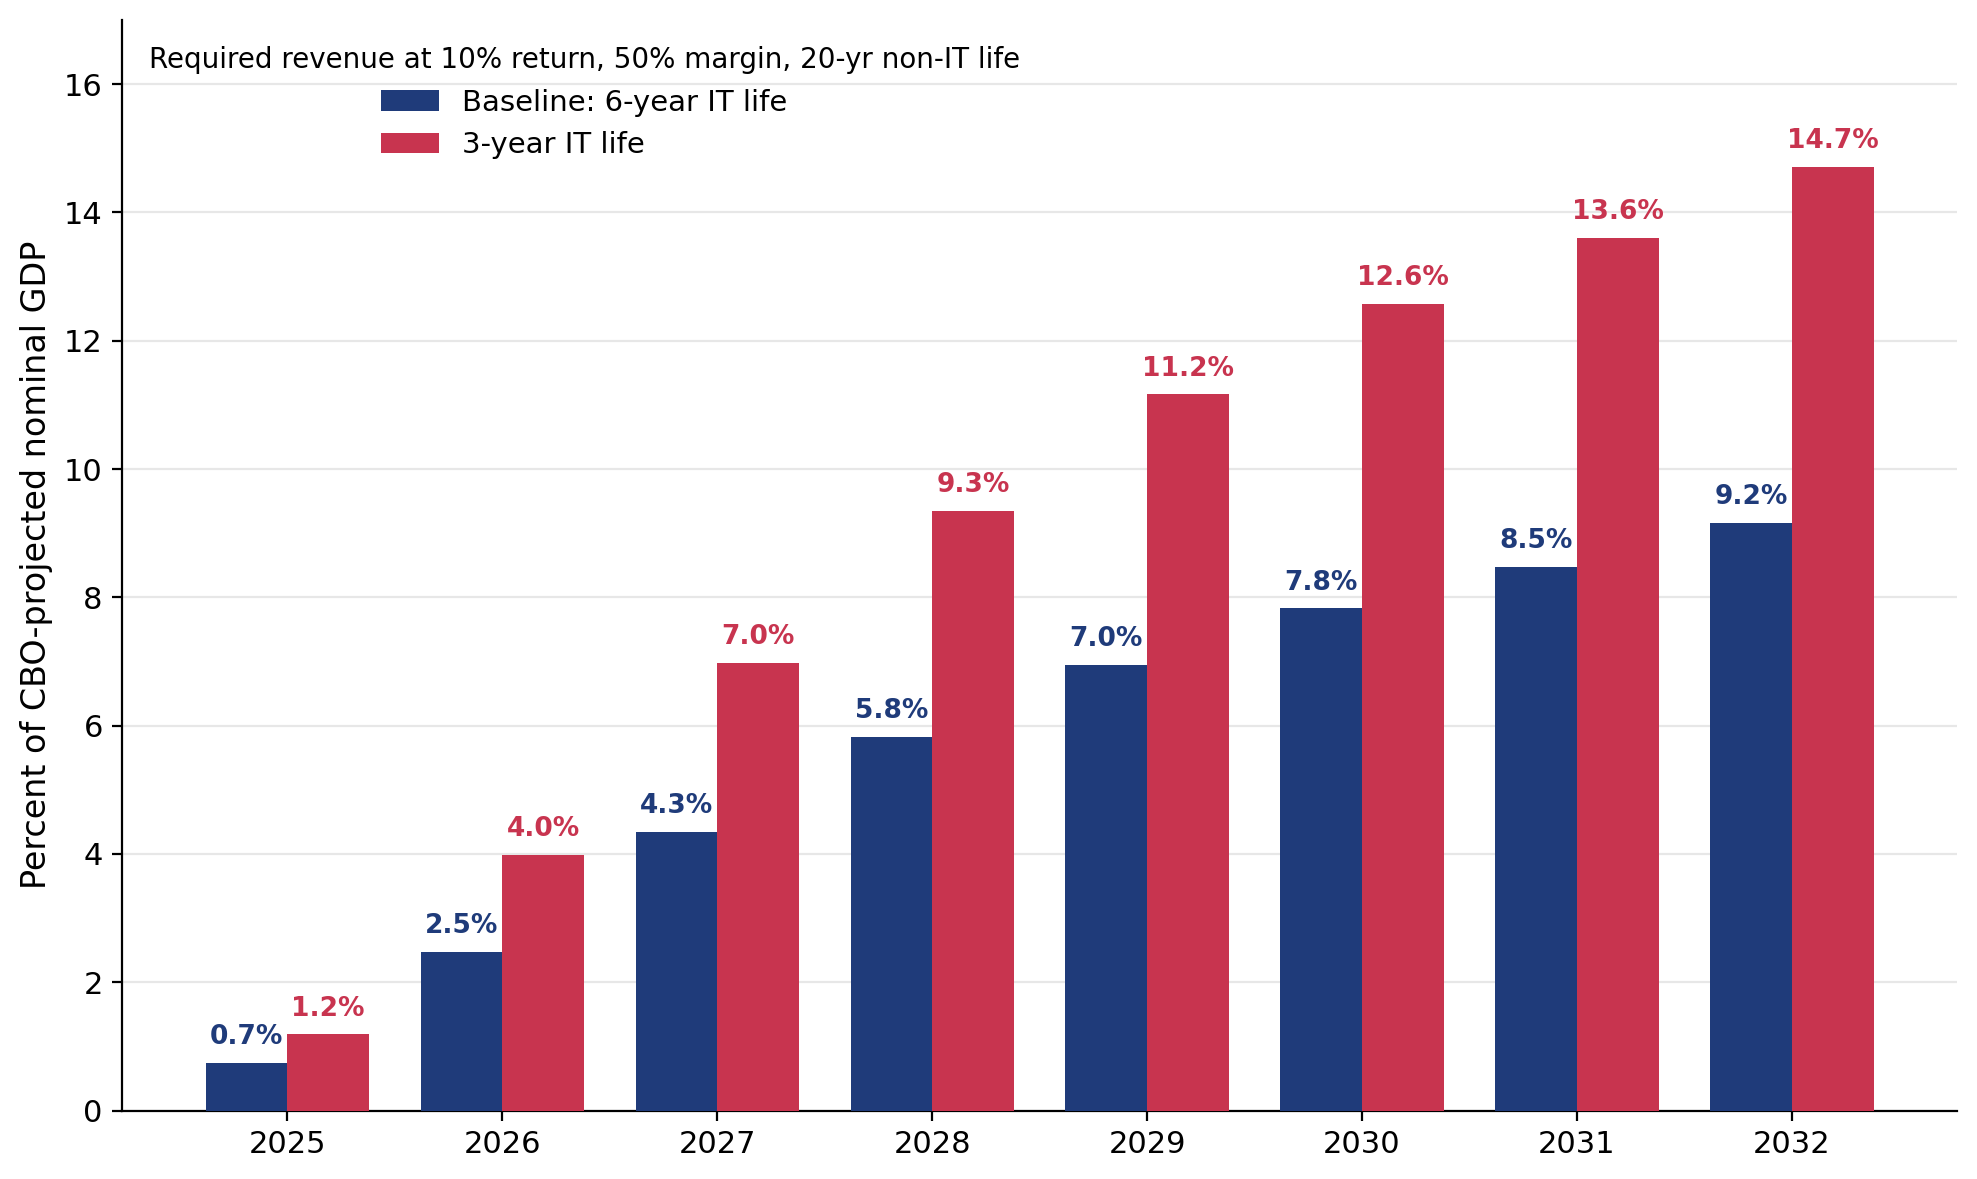
The 6-year IT life used by Stijn is (deliberately) generous. The problem is not that the physical hardware will stop running. It’s that customers may not be willing to pay $5.50 per GPU hour in 2032 for the 2026 chip. If you shrink the life of the IT to 3 years, that, of course, dramatically increases the required revenue, up from 9.2% of 2032 GDP to 14.7%. This is not completely out there. In fact, CoreWeave’s lenders reportedly use these assumptions.
It is useful to compare these numbers to those for the telecom buildout during the internet boom of the late 90s. We know how that story ended. We take BEA investment in equipment and structures for broadcasting and telecommunications and subtract wireless capex from CTIA, leaving the wired side. We apply the same arithmetic, with 8-year lives for equipment and 25-year lives for structures, a 40% cash-flow margin (closer to what telecom carriers actually earned), and a 10% required return. If anything, 10% is low: the 10-year Treasury yielded more than 6% in 1997.
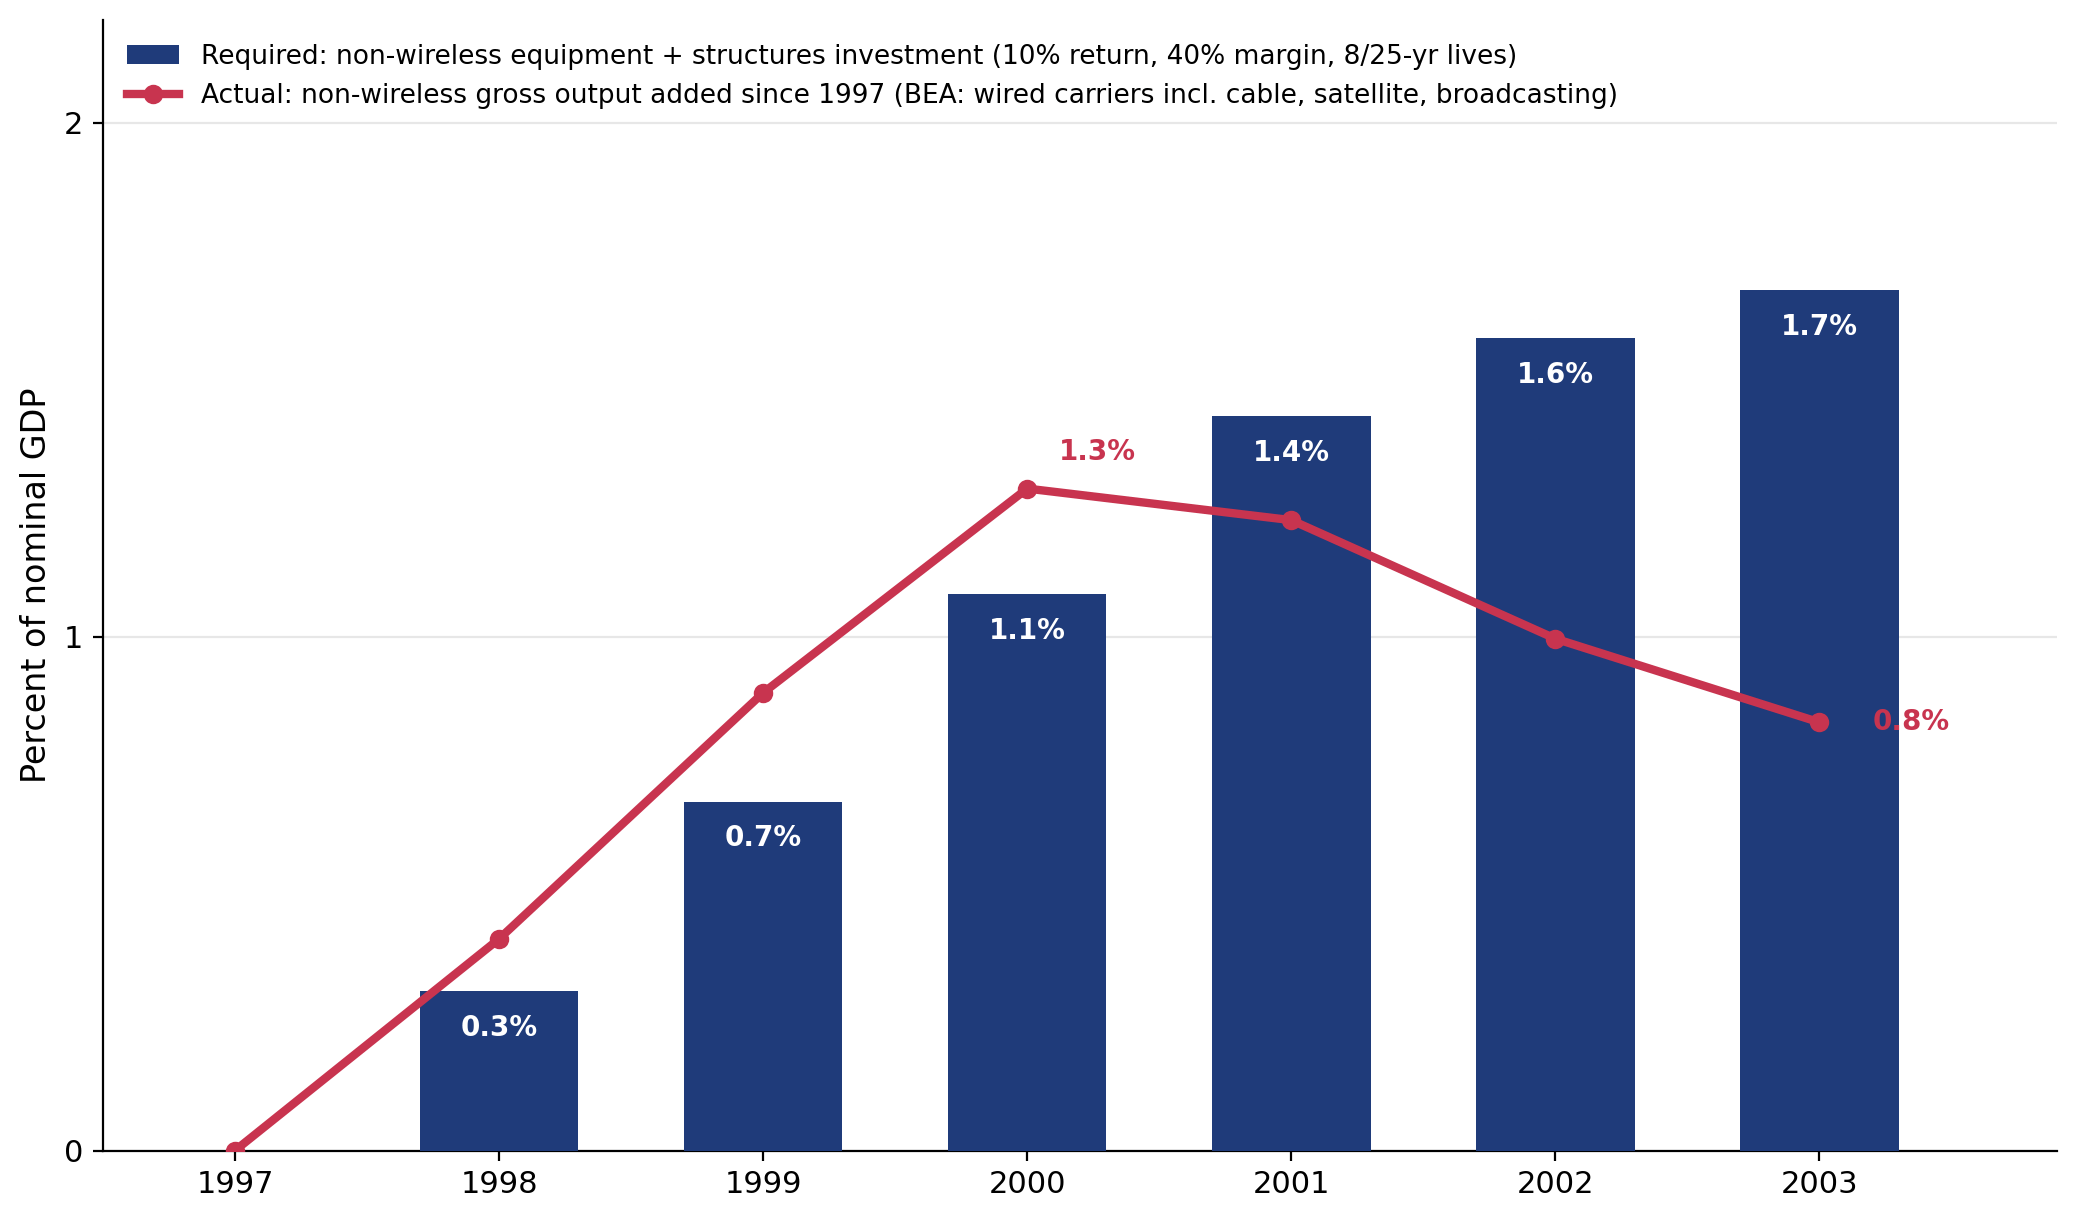
Between 1998 and 2003, the non-wireless part of the industry invested about $440 billion. To earn 10% on that investment, the industry needed $190 billion of additional revenue by 2003 or 1.7% of GDP. It only got $95 billion on top of its 1997 level, or 0.8% of GDP. The implied return on the telecom buildout was negative. The bust resulted in the bankruptcy of telecom firms like WorldCom, Global Crossing, and dozens of new local phone and fiber carriers.
There is no doubt that AI is a legitimate new general-purpose technology, just like the internet, but if you’re building out the infrastructure for this new technology, you have to worry about whether demand will show up fast enough in order for you to earn a reasonable rate of return before your hardware becomes obsolete. That’s the part that investors got wrong in the late 90s.
In the end, the U.S. economy was able to absorb these losses without too much trouble. Most of these were borne by shareholders and high-yield bondholders, not by levered financial institutions. Not a single bank had to be bailed out. It’s not clear whether that would be the case this time around. Stijn's paper shows the AI buildout is being financed instead through project debt, private credit, and 90%-levered special-purpose vehicles that sit off the hyperscalers' balance sheets. It’s an opaque mix. Until recently, the direct exposure of banks was more limited, but they may have been exposed indirectly through the credit they extend to the funds that invest in these data centers. Since 2025, banks have become more exposed. CoreWeave's 2023–24 GPU loans were funded by Blackstone, Carlyle, and the like, but every facility since mid-2025 has been syndicated to banks. 3
The AI buildout
Van Nieuwerburgh, Stijn (2026). “Financing the AI Buildout.” Brookings Papers on Economic Activity, conference draft, September 24–25, 2026. PDF. Tables 1, 5, 6, 7; Appendices B–D.
Cummings, Ryan, and Jared Bernstein (2026). “AI Companies Are In a Race Against Time.” The Intelligence Is Artificial, September 25, 2026. Link.
Shipp, Adam, and Kristian Beale (2026). “Can Hyperscalers Earn Their AI Ambitions?” LPL Research, July 27, 2026. PDF.
Congressional Budget Office (2026). The Budget and Economic Outlook: 2026 to 2036, February 2026, economic projections data file (calendar-year nominal GDP). Link.
Bureau of Economic Analysis. Fixed Assets Accounts, Tables 3.7E/3.7S (investment in private equipment and structures by industry) and 3.4E/3.4S (current-cost depreciation), industry “Broadcasting and telecommunications.” Data file.
Bureau of Economic Analysis. GDP by Industry, Underlying Detail, Table U.GO205-A, gross output by industry in current dollars (wired, wireless, satellite/other telecommunications; broadcasting). Data bundle.
CTIA. Semi-Annual Wireless Industry Survey, historical table of cumulative capital investment, 1985–2013. Background document.
USTelecom (2019). “U.S. Broadband Investment Continued Upswing in 2018,” Research Brief, July 31, 2019 (historical capex series 1996–2018). PDF.
Federal Communications Commission (2006). Telecommunications Industry Revenues: 2004, Industry Analysis and Technology Division. PDF.
This is a gross revenue number, not a value-added number. The 9.2% ratio is not a measure of the footprint of this industry in the U.S. economy. That ratio would be smaller.
In the paper’s own units it’s GPU-hour rental revenue: $3.725T works out to about $5.5 per installed GPU-hour at full utilization (~$6.9 at 80%), which he compares to current on-demand prices of $6–10+.
Every facility since mid-2025 (four deals, about $17 billion) has been syndicated to ten to thirteen banks, among them JPMorgan, MUFG, Morgan Stanley, Goldman, Citi and Wells Fargo.
Do you actually believe that?
The model claims $1,153bn and $1,432bn in data center investmets in the US in 2025 and 2026.
Seems extremely high and far too broad
The big seven hyperscalers and neoclouds report $459 and $879bn in capex in the same period; of which we estimate a maximum of 64% was AI data centers.
Where do you get $1.153bn in AI data centre investments in the US in 2025, and what explains the gap between that and what the dominant hyperscalers have publicly declared?
Very thought-provoking. To me, the math here is optimistic because it assumes monopolistic 50% operating margins. It's very unclear that the market structure underlying the AI buildout will develop the same way as railroads or the internet. Railroads are natural monopolies and many internet businesses are winner-take-all.
Chinese models are already taking share at the model level, and custom ASICS are competing for inference at the lowest cost. Why should we expect that AI infrastructure can achieve 50% margins?