

In one of his recent posts, Paul Krugman asked, “What are bond markets telling us?” His answer is: don’t panic. According to Krugman, yields are up mainly because of a surge in the demand for credit fueled by hyper-scalers building data centers, not necessarily because the markets doubt the long-run fiscal health of the US.
Krugman brings a couple of pieces of evidence to the table. He starts by discussing the evidence from CDS markets. As it turns out, you can buy insurance against a default by the U.S. Treasury. This insurance contract may be sold to you by a large financial institution. And while the contract is typically collateralized and mark-to-market on a daily basis, in the unlikely event that the Treasury actually defaults, you —the purchaser of insurance —would still be exposed to a significant amount of counterparty risk on that very day that’s not covered by the collateral.1 On the day it triggers, the protection seller has to produce something like 45 cents on the dollar, in cash, all at once, in a funding environment where a Treasury default has just occurred. Most of that is not covered by the posted collateral. It doesn't help that the eligible collateral includes U.S. Treasuries, which would be impaired by the default. Your counterparty would probably be having a really bad day because the U.S. Treasury just defaulted. That’s a little bit concerning as well. All these factors put together mean that your willingness to pay for insurance against default by the U.S. Treasury is probably not a true reflection of the risk-neutral probability of default and the resulting losses.
Not surprisingly, transaction volume in these US Treasury CDS markets is also tiny compared to trade in other single-name CDS contracts, although the volume briefly spiked in 2023, the latest US debt ceiling episode. And even then, there were more trades in Marks and Spencer CDS, and the total notionals were tiny. Outside of these episodes where market participants are concerned about technical defaults, these US Treasury CDS markets are essentially dormant. No transactions sometimes for weeks. Market participants don’t really seem to buy these contracts in order to acquire insurance against genuine U.S. credit events, but they mainly use it for doing small arbitrage trades.
So Krugman is right that there's no panic signal in these prices. It's just that the instrument is too weak to send much of a signal.
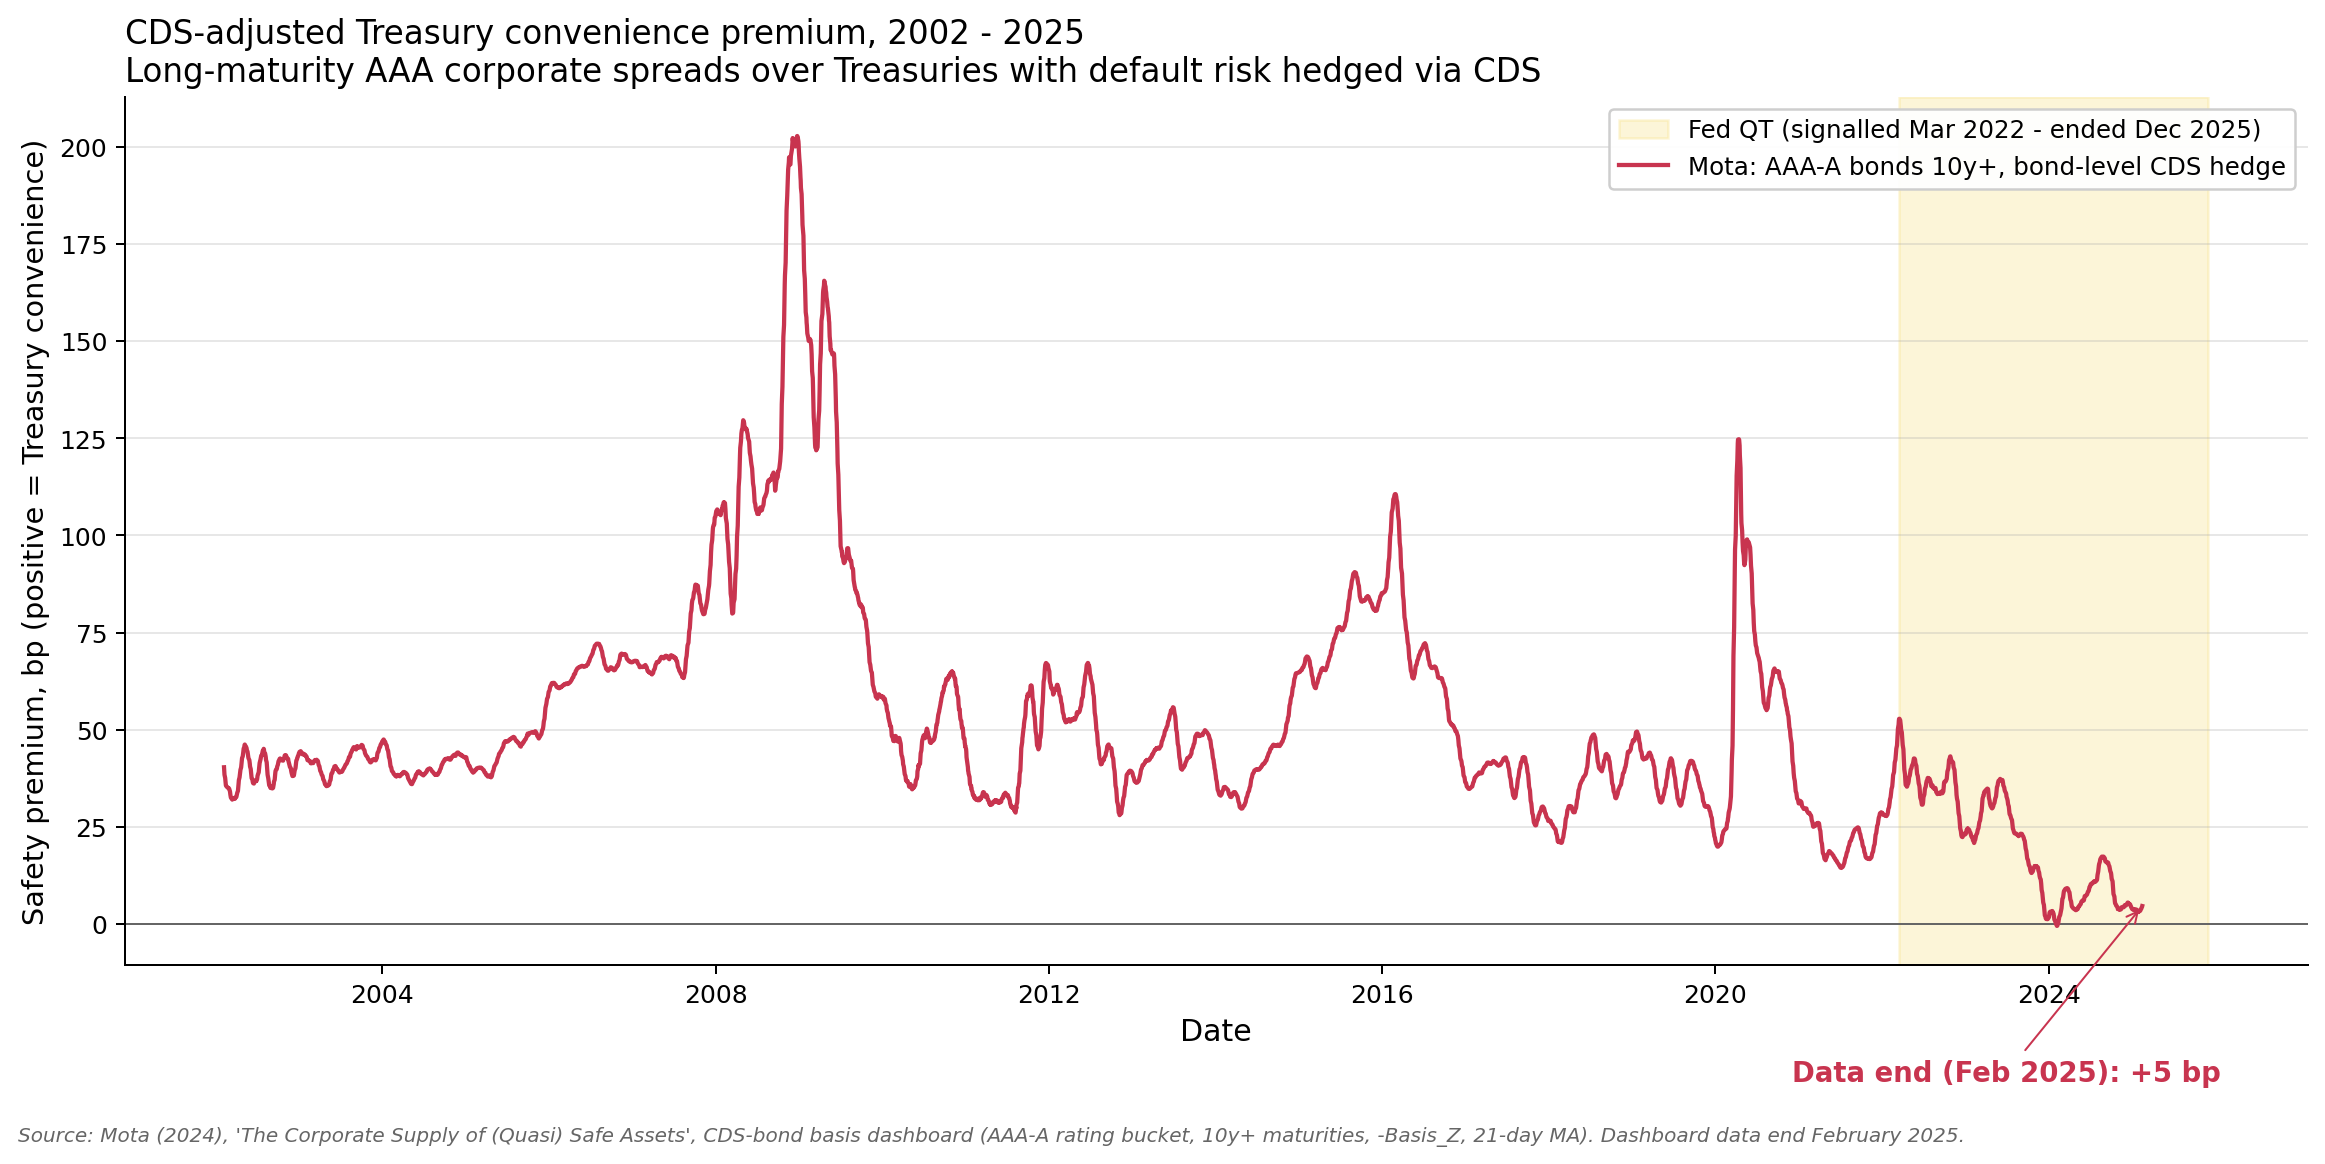
A more useful gauge of how safe investors think U.S. Treasuries are is a careful comparison of Treasuries to close substitutes, like AAA corporate bonds. That’s exactly what MIT’s Lira Mota does. She compares U.S. Treasuries to AAA corporates and then adds some additional credit insurance for those corporate bonds on CDS markets in order to make it a clean apples-to-apples comparison.2 We’ve now essentially manufactured a synthetic U.S. Treasury from AAA corporate bonds by buying credit insurance. The figure below plots the spread over Treasuries. Economists call this the convenience yield, the yield investors are willing to forgo for the safety and liquidity of Treasuries. Over the last couple of years, the convenience yield has completely disappeared.
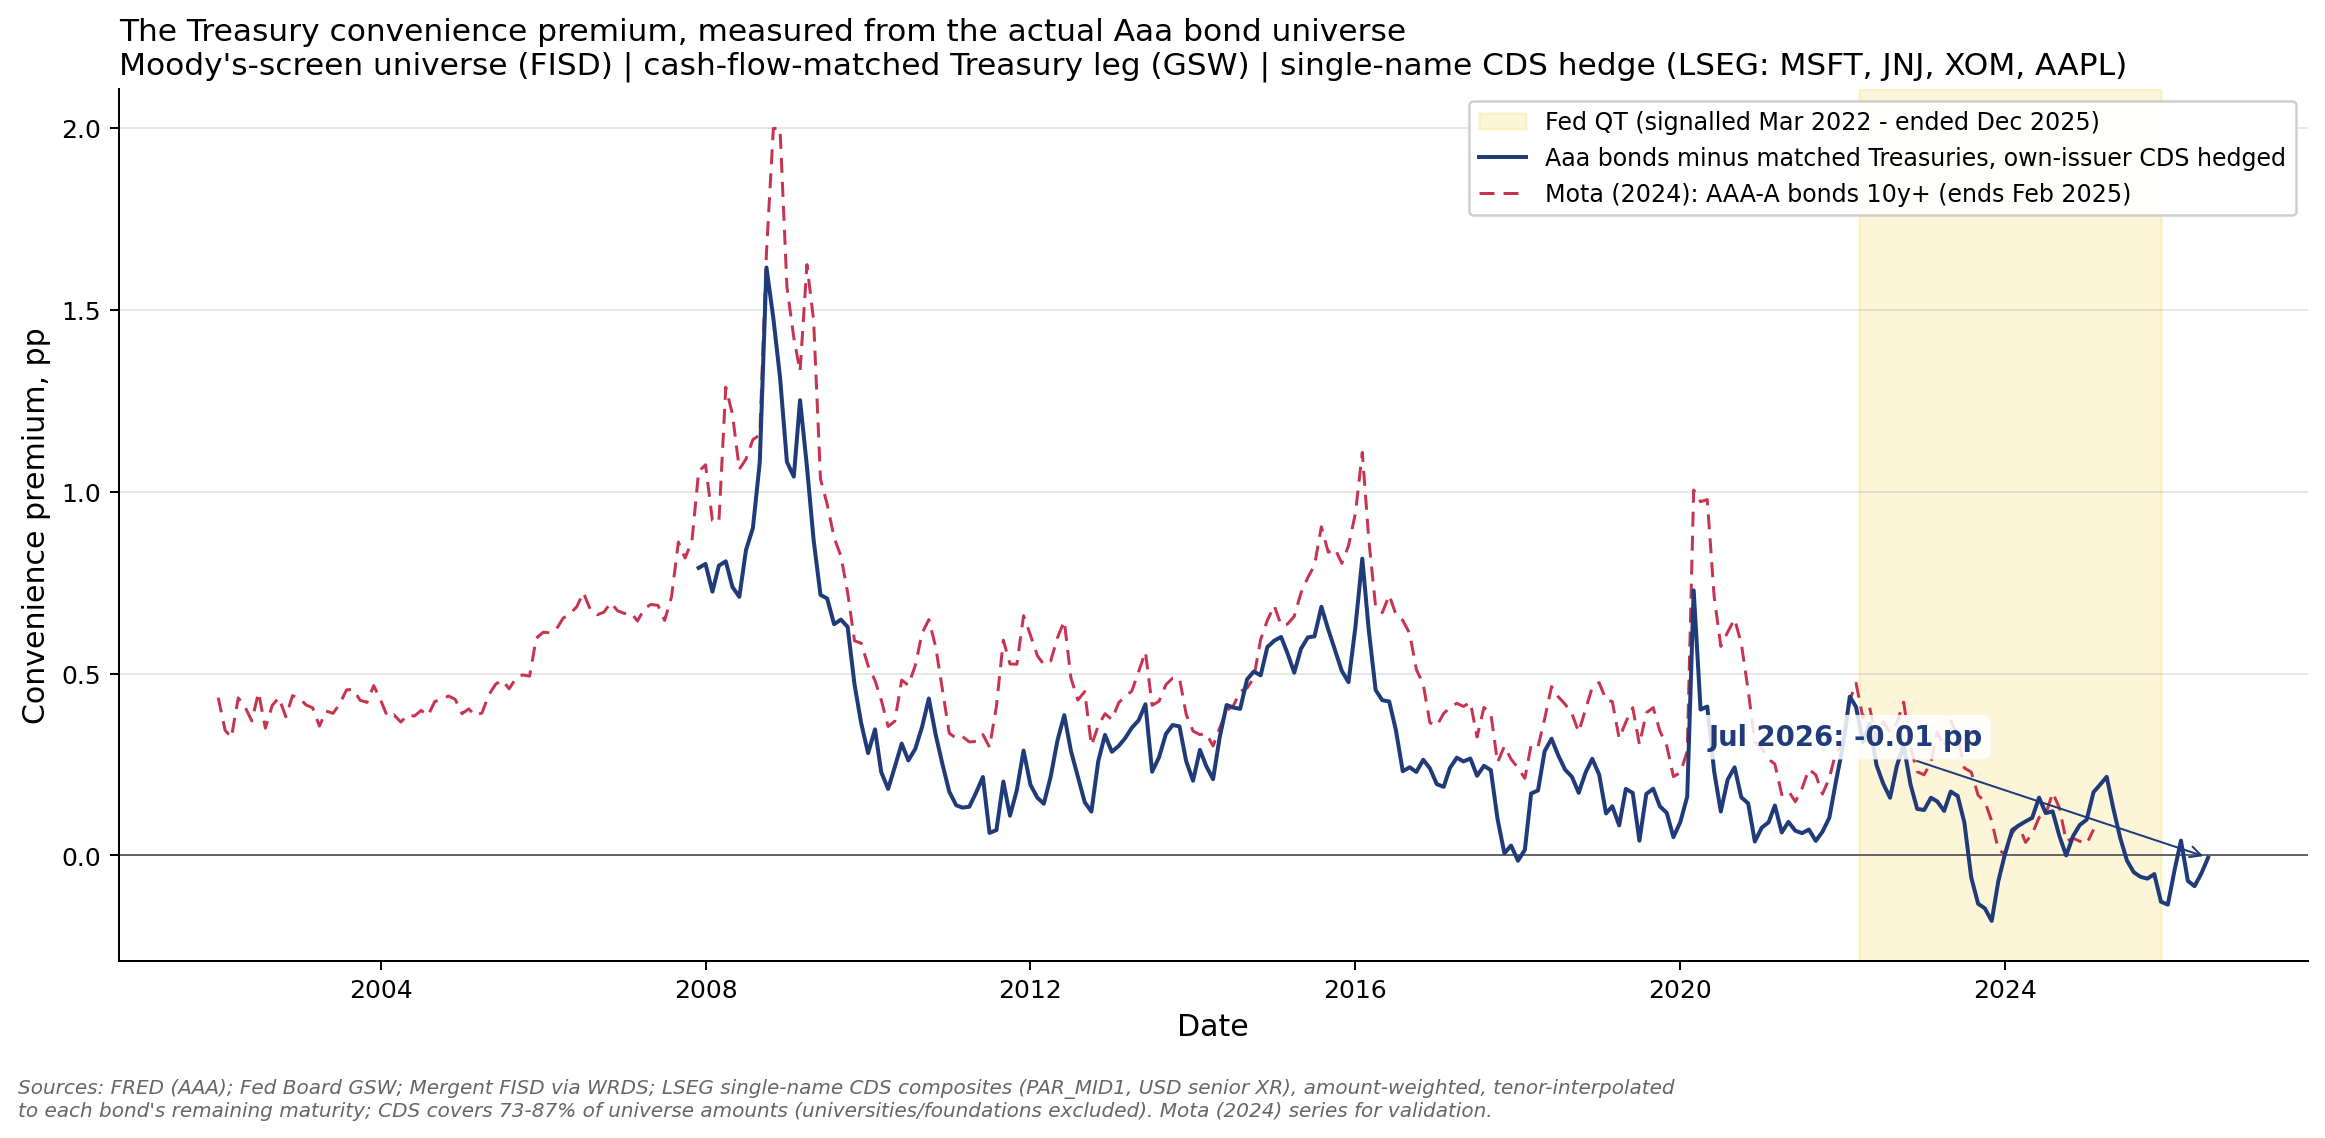
I’ve extended the data using an approach similar to Mota’s until last July, 2026.3 The convenience yield on Treasuries is still around zero. Investors seem to be indifferent between Treasuries and AAA corporates when it comes to safety and liquidity. That’s really bad news for US taxpayers.
If you’re worried that there aren’t enough AAA single names in the basket, you can do the same thing for BBBs, and you’ll get very similar results.
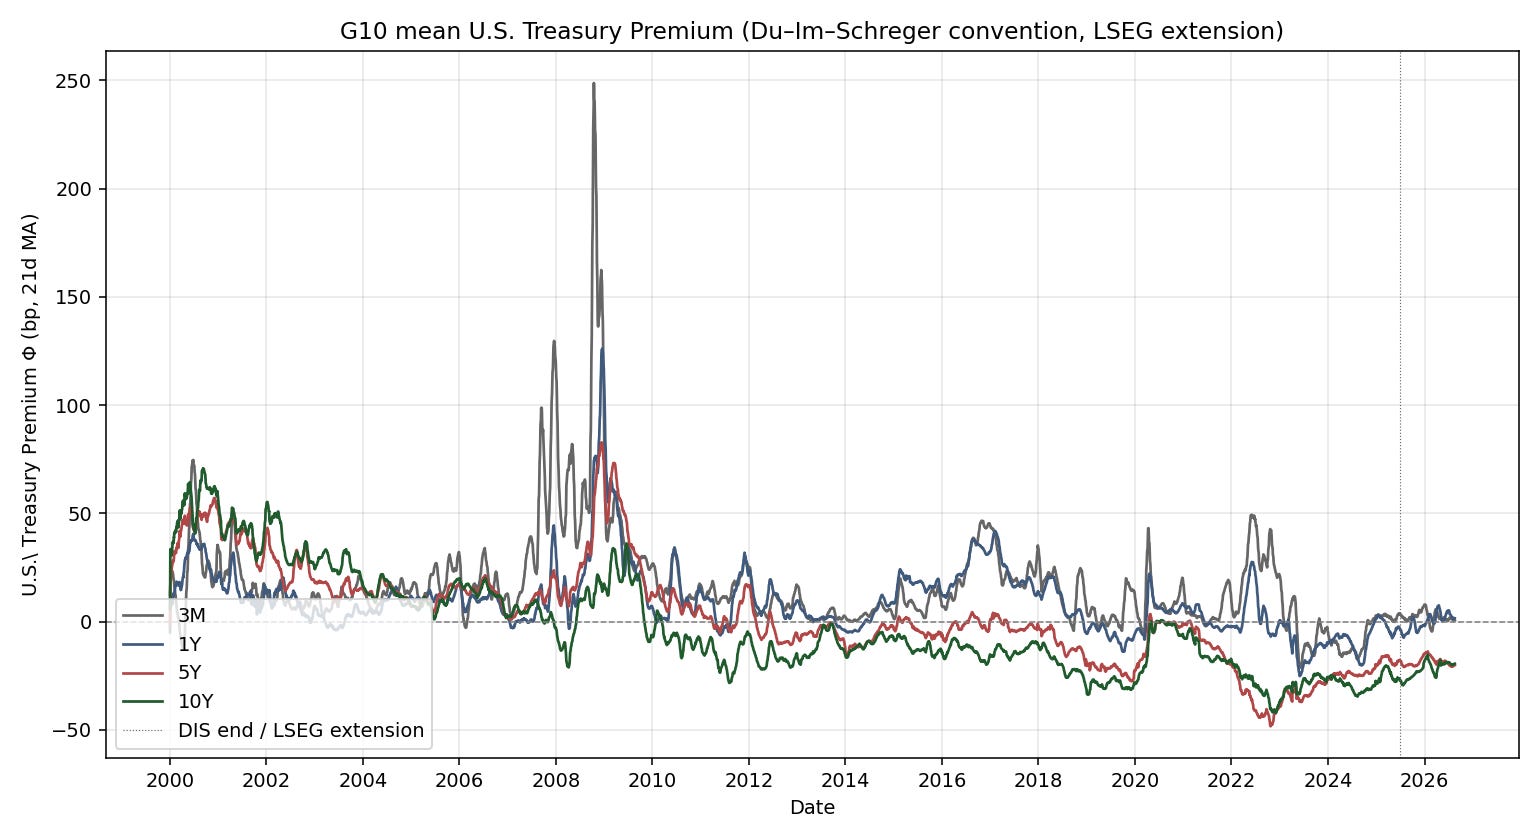
Here’s another useful comparison. We can compare Treasuries to G10 foreign sovereign bonds. We can swap the foreign currency coupon payments back into dollar payments using cross-currency basis swaps. That’s exactly what Wenxin Du and Jesse Schreger do, and what I have done in my work with Zhengyang Jiang and Arvind Krishnamurthy. The figure below plots the Du-Im-Schreger measure of the U.S. Treasury premium, or the convenience yield: foreign currency-hedged yield minus Treasury yield. That measure is either zero or negative at all tenors. In other words, the U.S. Treasury is now borrowing at higher rates than other G-10 countries if you do an apples-to-apples comparison. Even at shorter maturities, the convenience yield seems to be completely gone.
And, finally, the stock-bond correlation has flipped signs in the last few years. Treasuries used to be a reliable hedge against stock market risk, but that has changed since the pandemic.
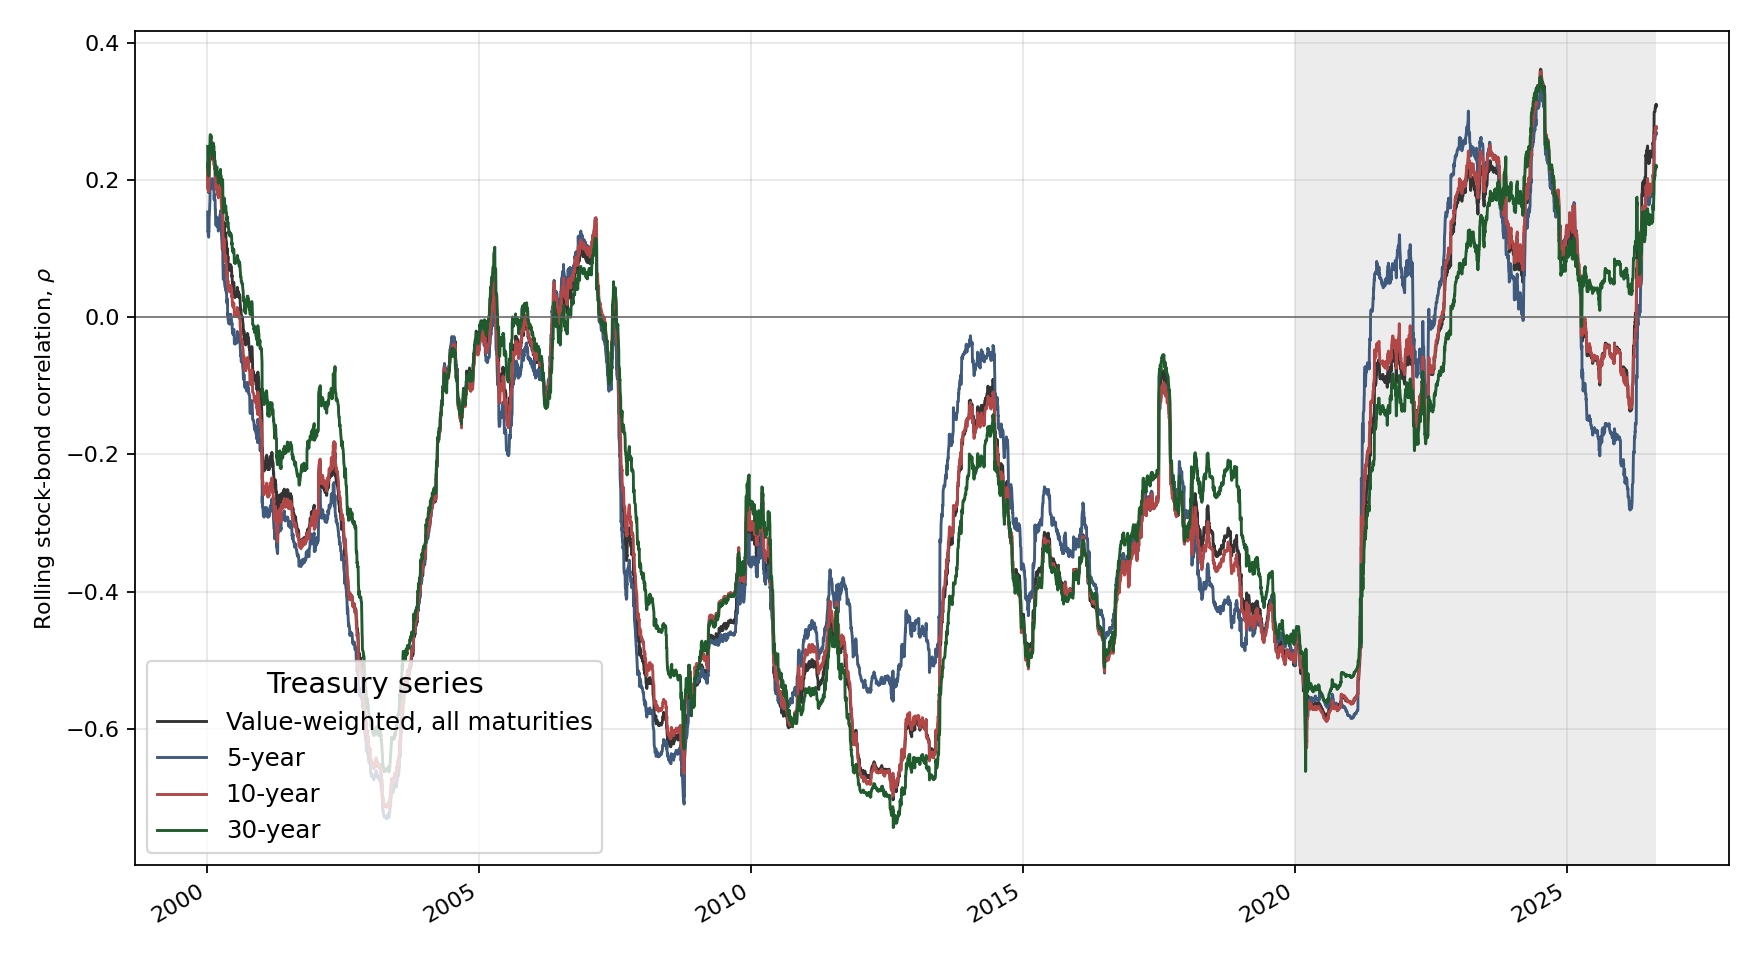
Yields are up because investors don’t think of Treasuries as safe —zero beta or negative beta — assets any longer. A substantial part of the increase in Treasury yields can be accounted for by a decline in the safety premium or the convenience yield on Treasuries. That’s really bad news for US taxpayers because they no longer get to sell IOUs at a premium when every other government is struggling to fund itself. Maybe it’s not cause for panic, but it’s definitely cause for some reflection on the US’ fiscal trajectory.
Write-up based on: “America’s Risky Debt: What Markets See That Policymakers Don’t.”
References
The Krugman post
Krugman, Paul. 2026. “What Are Bond Markets Telling Us?” Paul Krugman (Substack), August 19.

On U.S. sovereign CDS
Benzoni, Luca, Christian Cabanilla, Alessandro Cocco, and Cullen Kavoussi. 2023. “What Does the CDS Market Imply for a U.S. Default?” Economic Perspectives No. 4. Federal Reserve Bank of Chicago. https://www.chicagofed.org/publications/economic-perspectives/2023/4
Boyarchenko, Nina, and Or Shachar. 2020. “The Evolving Market for U.S. Sovereign Credit Risk.” Liberty Street Economics, Federal Reserve Bank of New York, January 6. https://libertystreeteconomics.newyorkfed.org/2020/01/the-evolving-market-for-us-sovereign-credit-risk/
Chernov, Mikhail, Lukas Schmid, and Andres Schneider. 2020. “A Macrofinance View of U.S. Sovereign CDS Premiums.” Journal of Finance 75 (5): 2809–2844.
Klingler, Sven, and David Lando. 2018. “Safe Haven CDS Premiums.” Review of Financial Studies 31 (5): 1856–1895.
Augustin, Patrick, Mikhail Chernov, and Dongho Song. 2020. “Sovereign Credit Risk and Exchange Rates: Evidence from CDS Quanto Spreads.” Journal of Financial Economics 137 (1): 129–151.
On convenience yields and the Treasury premium
Mota, Lira. 2024. “The Corporate Supply of (Quasi) Safe Assets.” Working paper. https://papers.ssrn.com/sol3/papers.cfm?abstract_id=3732444
Du, Wenxin, Joanne Im, and Jesse Schreger. 2018. “The U.S. Treasury Premium.” Journal of International Economics 112: 167–181.
Krishnamurthy, Arvind, and Annette Vissing-Jorgensen. 2012. “The Aggregate Demand for Treasury Debt.” Journal of Political Economy 120 (2): 233–267.
Jiang, Zhengyang, Arvind Krishnamurthy, and Hanno Lustig. 2021. "Foreign Safe Asset Demand and the Dollar Exchange Rate." Journal of Finance 76 (3): 1049–1089. https://doi.org/10.1111/jofi.13003
Related work of mine
Lustig, Hanno. 2026. “America’s Risky Debt: What Markets See That Policymakers Don’t.” In The American Economy in a New Era, edited by Melissa S. Kearney and Luke Pardue. Washington, DC: Aspen Institute. https://www.economicstrategygroup.org/publication/americas-risky-debt-what-markets-see-that-policymakers-dont/
Gómez-Cram, Roberto, Howard Kung, Hanno Lustig, and David Zeke. 2025. “Fiscal Redistribution Risk in Treasury Markets.” NBER Working Paper No. 33769. https://www.nber.org/papers/w33769
Gómez-Cram, Roberto, Howard Kung, Hanno Lustig, and David Zeke. 2026. “Government Funding Costs Under Financial Repression.” Working paper, Stanford GSB and London Business School.
CDS on U.S. sovereign risk (often loosely called “U.S. Treasury CDS”) are not part of the U.S. mandatory central-clearing set. U.S. sovereign CDS are currently not centrally cleared at ICC. So in practice they should be treated as predominantly bilateral/uncleared.
A substantial single-name corporate CDS segment is centrally cleared, and volume for all corporate CDS dwarfs volume for CDS on Treasuries.
I extended Mota's CDS-adjusted convenience premium past her February 2025 dashboard cutoff by rebuilding her measure from first principles on the actual Moody's Aaa bond universe: pulling the FISD-screened issuer set from WRDS, cash-flow-matching each bond to a synthetic Treasury off the GSW zero curve, and hedging default risk with single-name CDS (MSFT, JNJ, XOM, AAPL) from LSEG rather than her original Markit-sourced CDS-bond basis. The result runs through July 2026 and shows the same conclusion hers implied: the Treasury convenience premium has fallen to roughly zero.
I’m sorry, but any time Krugman tries to prognosticate on markets or most things, my priors tell me not to listen
Now and Then :) https://www.wsj.com/opinion/let-the-bond-market-speak-81529d74
https://www.wsj.com/articles/quantitative-tightening-not-now-11544991760